Citi just dropped its best-ever offer on the priciest card in the AAdvantage stable: 125,000 bonus miles after $15,000 in purchases within the first five months. The offer is labeled "limited time" and, per the usual pattern, will almost certainly shrink back to the 70k-100k range within weeks. If you're even thinking about it, the window is closing.
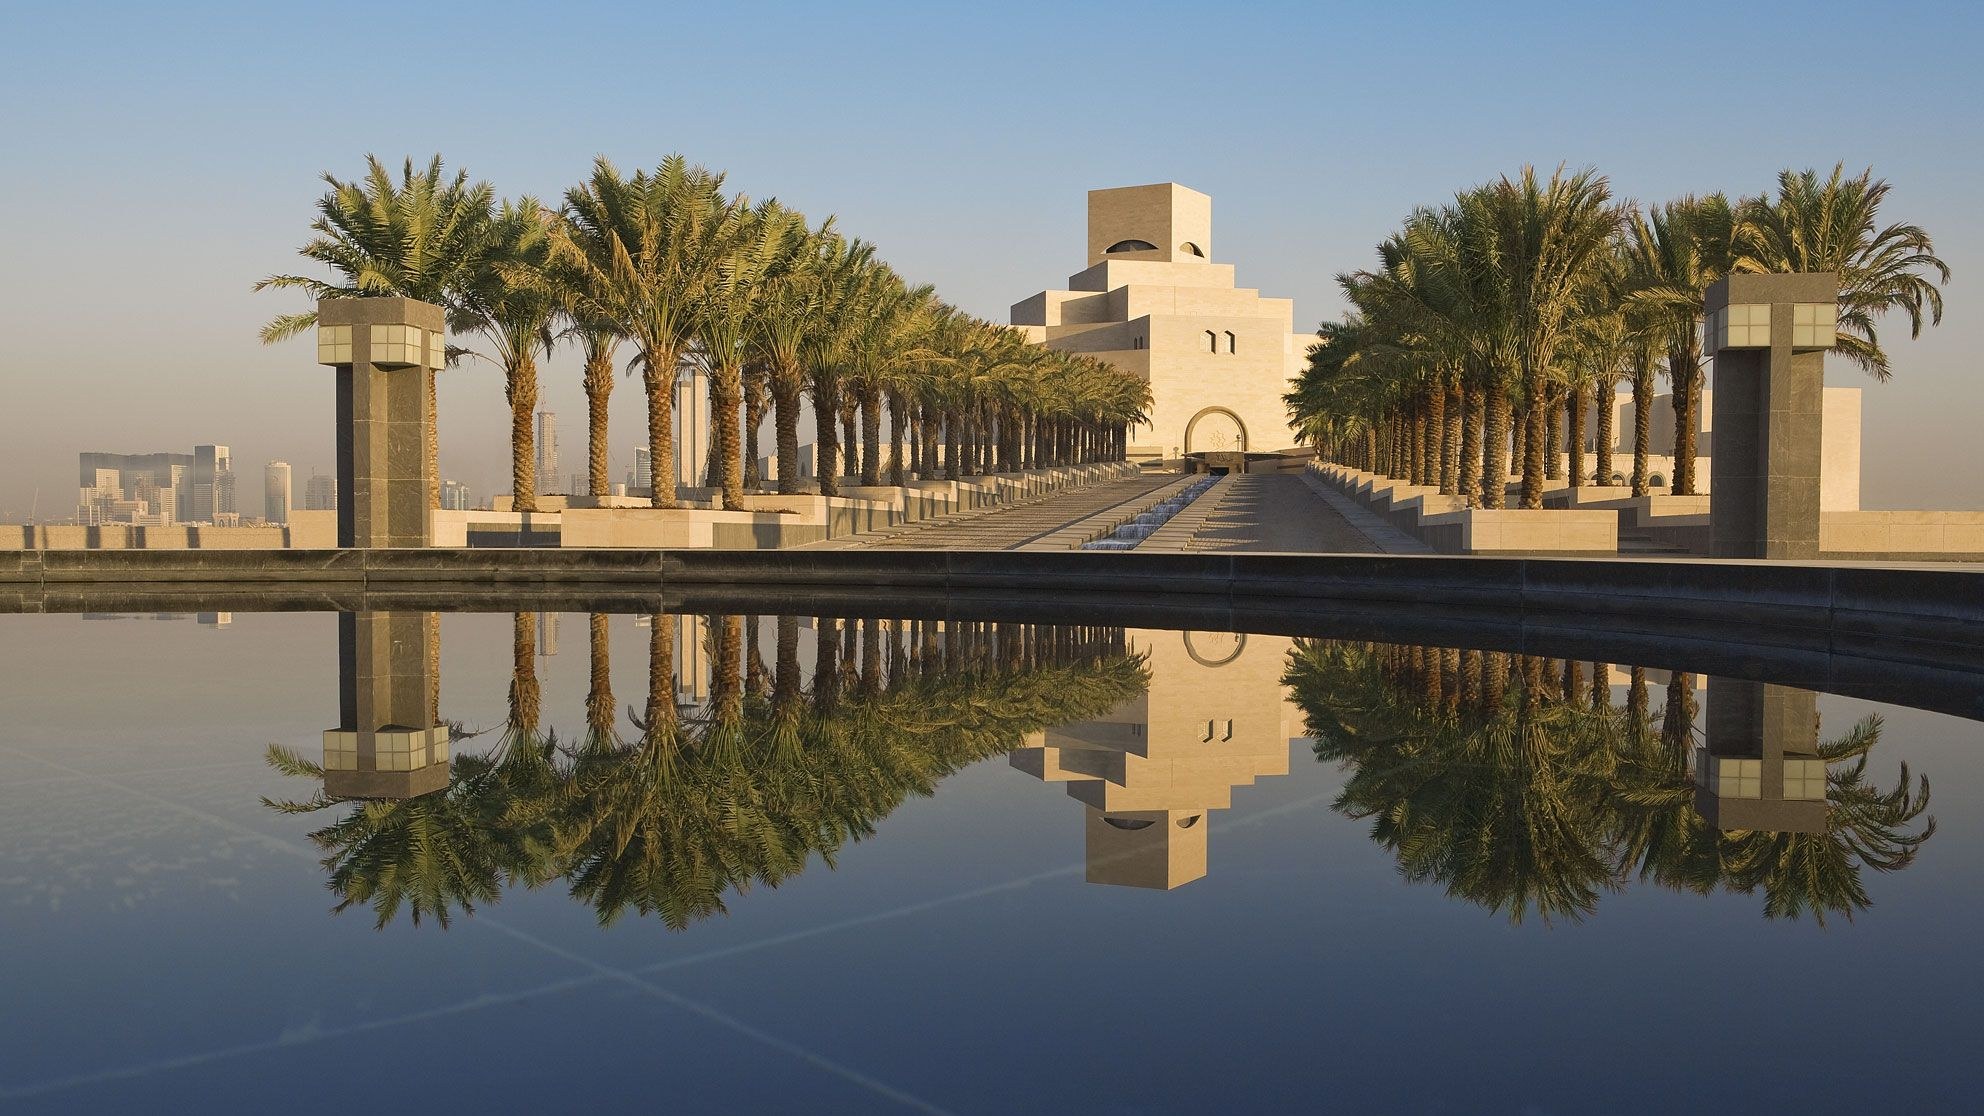
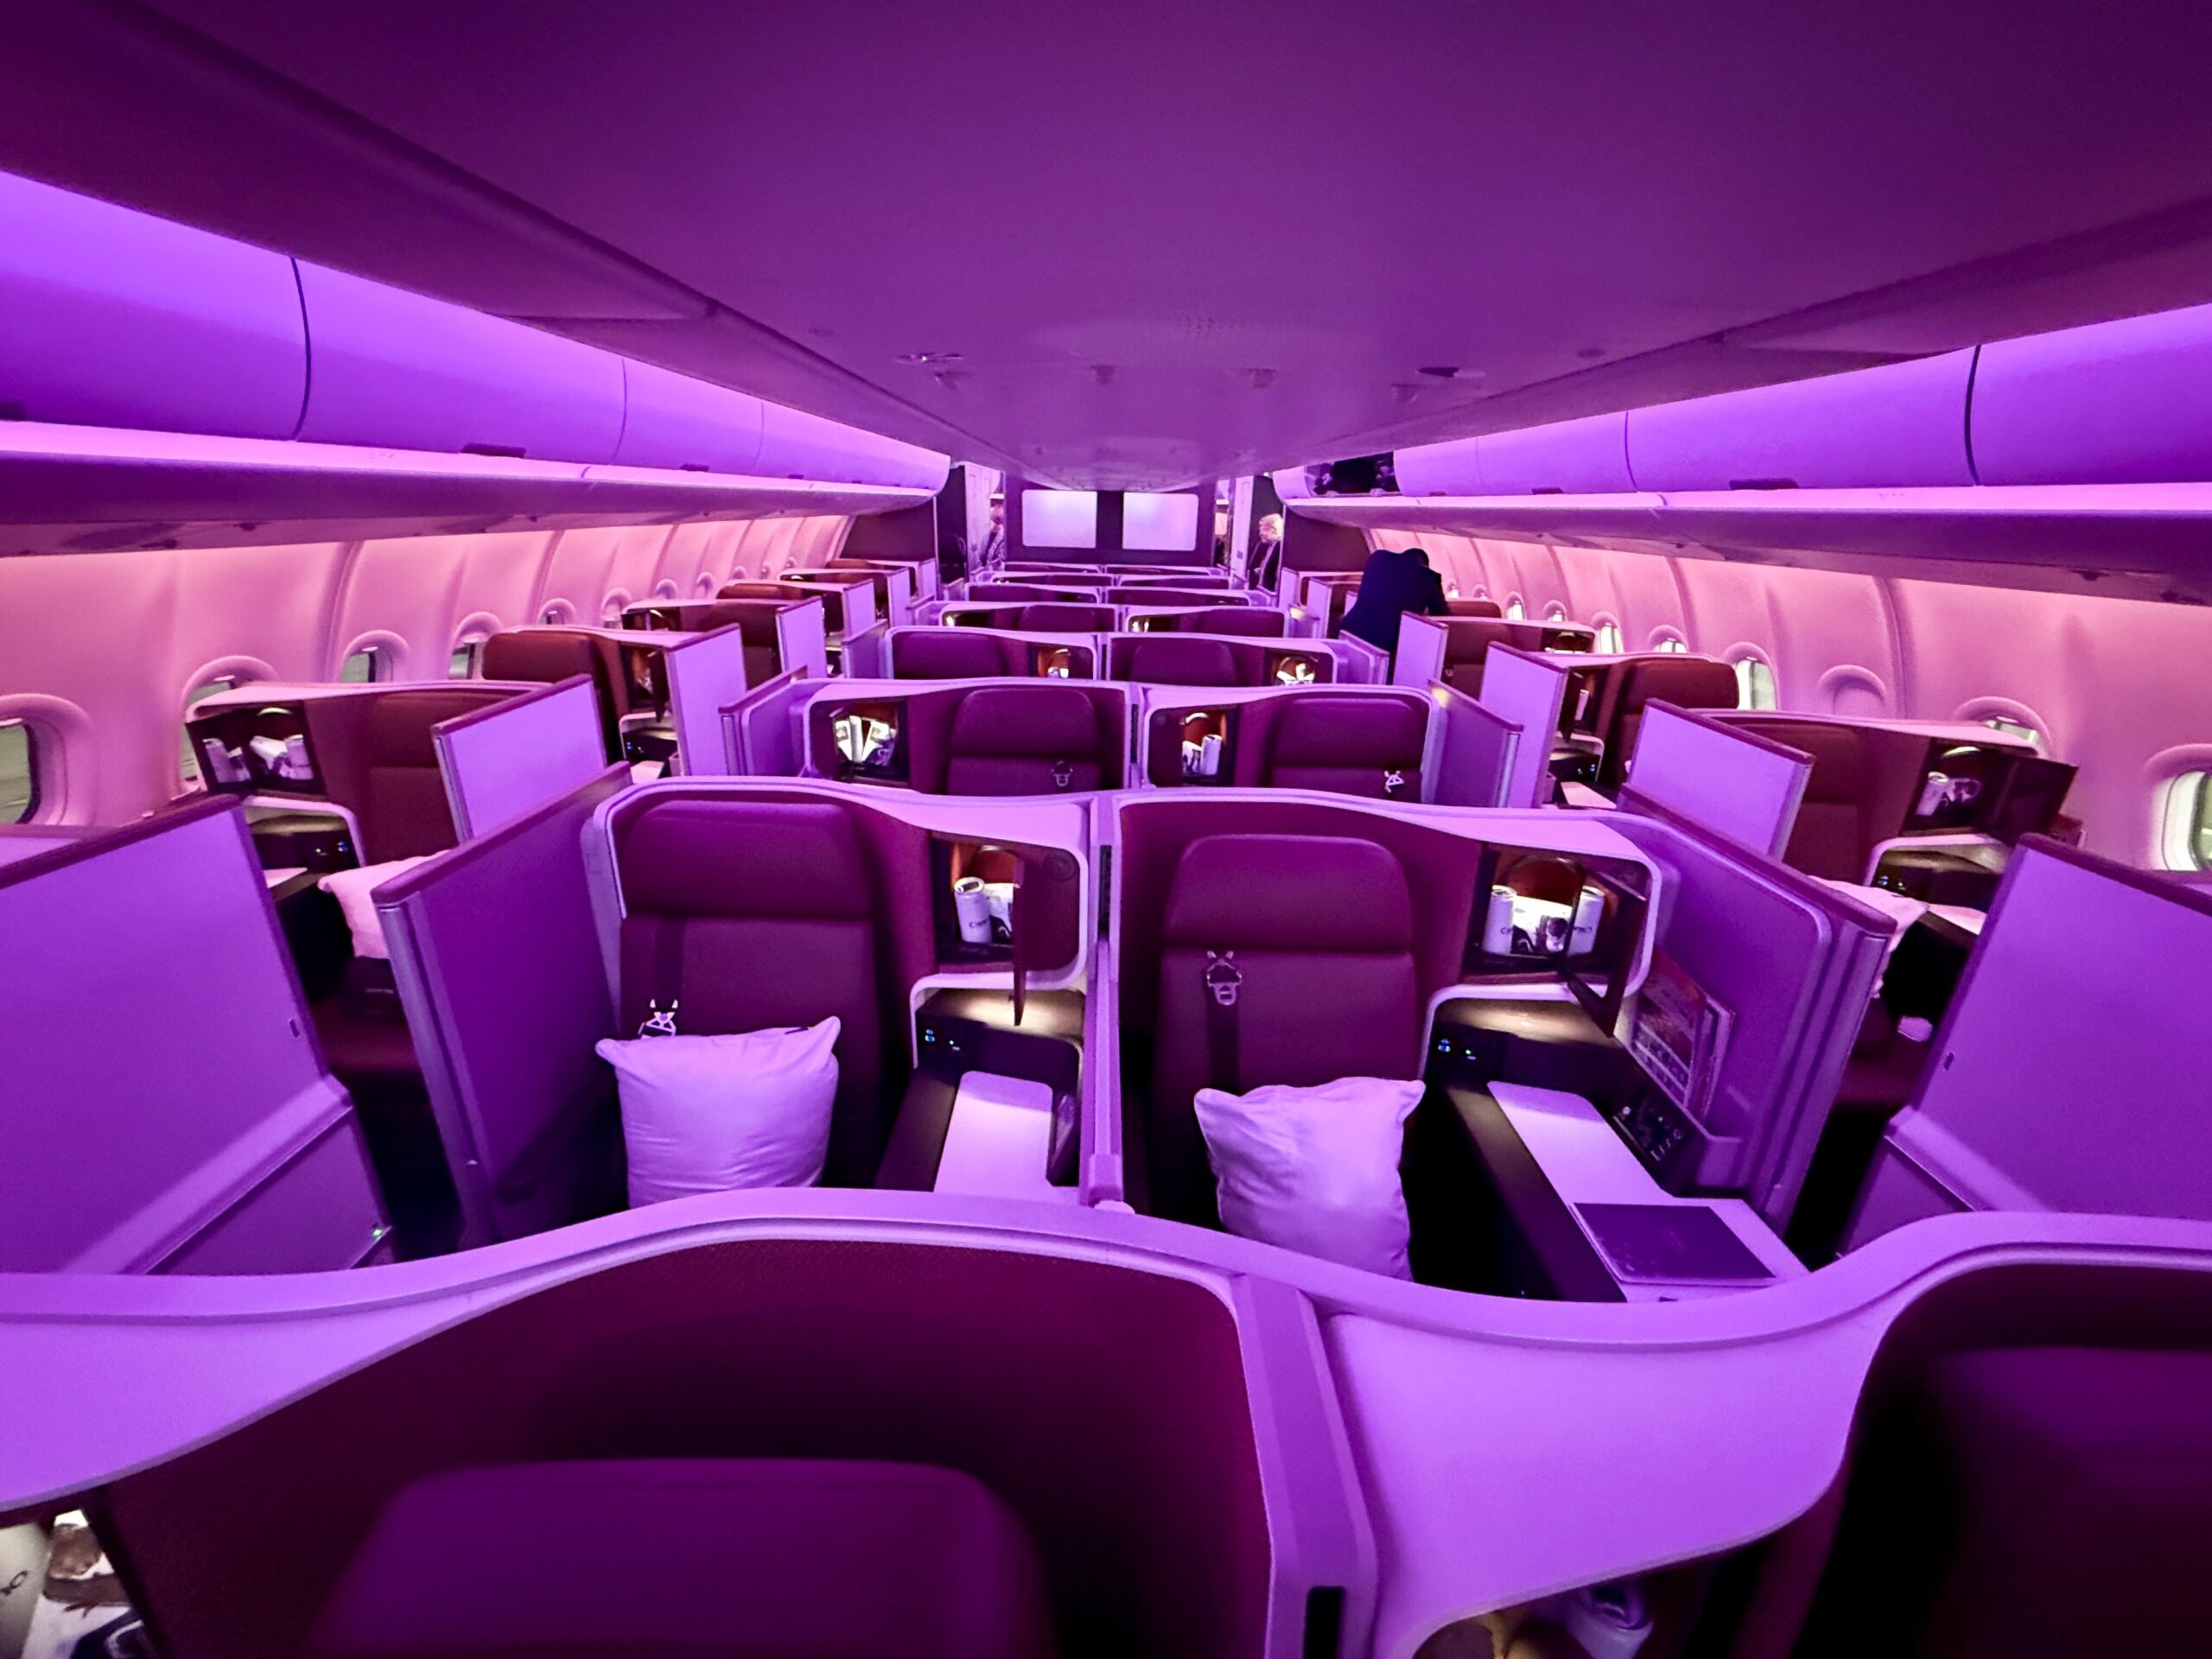
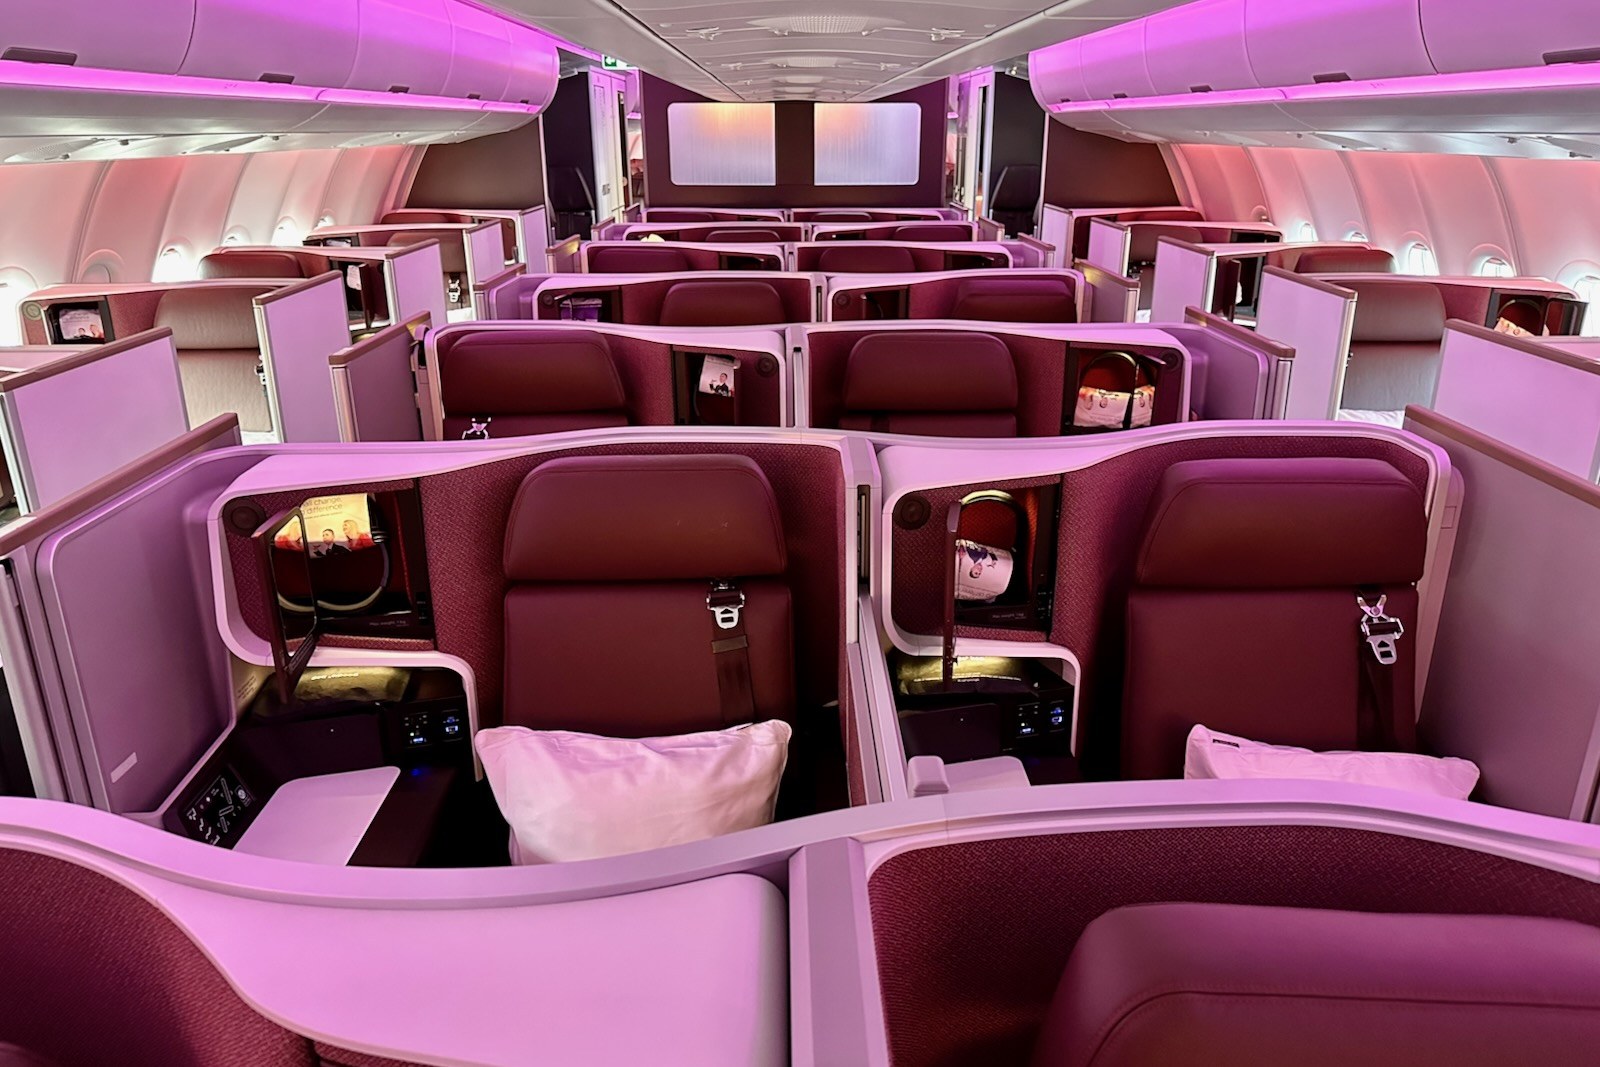
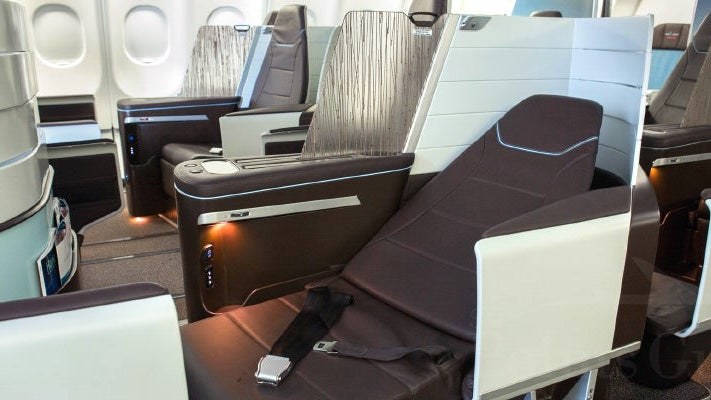
At current valuations around 1.5 cents per mile, those 125k miles are worth roughly $1,875. That's not theoretical. Book a one-way business class award to Europe on a partner like Iberia or Finnair and you're looking at 57,500 miles. Asia sweet spots are even better: 60,000 miles one-way to Japan or Korea on JAL in business class, or 70,000 for Qatar Qsuite to Doha. Two round-trips in premium cabins and the bonus has paid for itself with change left over for a decent bottle of Champagne at the Admirals Club bar.
The Perks That Actually Matter
The card's $695 annual fee (up from $595 after the 2026 refresh) gets you a full Admirals Club membership — not the watered-down version — plus access for up to two guests or immediate family. For anyone routing through DFW, CLT, or ORD more than a handful of times a year, this alone can justify the fee. Add Flagship Lounge access when flying international business on AA, free checked bags for you and up to eight companions, and a $500 annual AA Vacations credit split across two halves of the year, and the effective cost drops fast for the right user.
There's also up to $100 in annual inflight or Admirals Club credits, Global Entry/TSA PreCheck reimbursement, and the ability to earn up to 40,000 Loyalty Points per year toward elite status. The card earns a mediocre 4x on AA purchases (jumping to 5x after $150k annual spend) and a pathetic 1x everywhere else, so treat it as a bonus vehicle, not a daily driver.
The Math on the Bonus
$15,000 over five months is $3,000 a month. Manageable if you have a business, a big household, or the stomach for manufactured spend that won't get you shut down. You'll also earn about 15,000 base miles on that spend, bringing your total haul closer to 140k. Compared to the prior high of 100k after $10k in three months, this is more miles for more spend but with twice the runway. History says these peaks don't last.
Citi's rule on this card is straightforward: no bonus if you've received one on the Executive in the past 48 months, or if you converted another Citi AAdvantage card that earned a bonus in that window into the Executive. Having the Platinum Select or other AA cards is fine. Each product has its own clock.
Important note for Chase ecosystem players: Citi cards, including this one, count toward Chase's 5/24 rule. A new personal Citi approval will add one to your total new cards in the last 24 months. If you're at four, this could lock you out of Sapphire Reserve or Ink Preferred until it ages off. Plan your applications accordingly.
Is It Worth the Hard Pull?
For frequent AA flyers who actually use lounges and have premium redemptions lined up, yes. The combination of 125k miles, lounge access, and status acceleration can easily clear $2,500 in value in year one. For everyone else — especially those with existing lounge access via Priority Pass, Amex, or Chase cards — it's a harder sell. The annual fee isn't waived first year, and the earning rates won't excite anyone who isn't already all-in on American.
These elevated offers have a habit of disappearing right when you finally decide to pull the trigger. If the numbers work and you won't be sitting on unused miles, apply today. Otherwise, let someone else fund Citi's latest experiment in seeing how high they can push the annual fee before people revolt.
Action item: Check your 48-month bonus history with Citi, run the numbers against your actual AA flying and lounge usage for the next 12 months, confirm you're safely under 5/24 if Chase cards matter to you, and apply before the offer reverts to its usual mediocre self. The miles won't book themselves.